
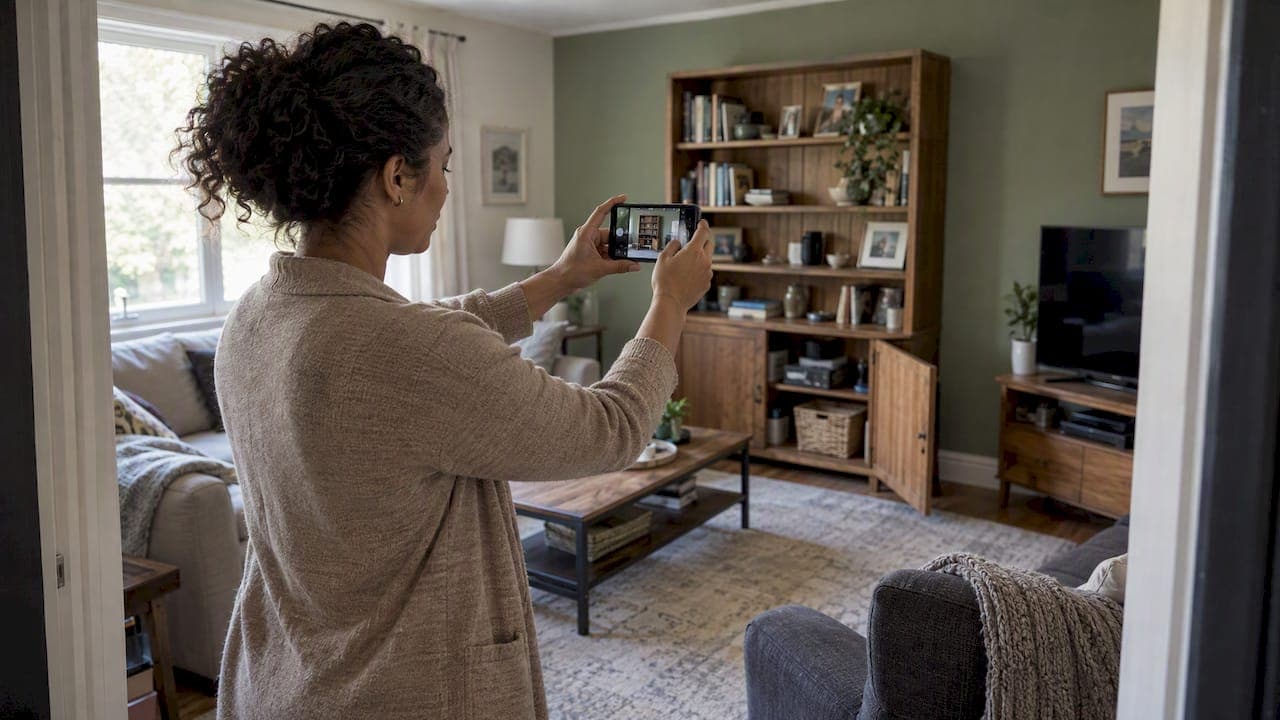
There is no separate policy called "home inventory insurance." A home inventory is a record of what you own, and you use it to buy the right amount of homeowners, condo or renters coverage and to prove your loss if you ever file a claim. Build it room by room, with photos or video, a value for each item and copies of receipts, then store a copy somewhere other than your house. The steps are below.
TL;DR
- A home inventory is a list of your belongings with photos, values, serial numbers and receipts. It is not an insurance product.
- Without one, insurers may default to estimating item values, which can lead to underpayment.
- Go room by room, record age, purchase price, estimated current value, and model and serial numbers.
- Keep copies in at least two places and update the list a few times a year.
- Use the total to check that your personal property limit and your replacement cost or actual cash value setting fit what you own.
Table of Contents
- What people mean by home inventory insurance
- Why an inventory changes how a claim goes
- What to record for every item
- How to build the inventory in an afternoon
- Apps, spreadsheets and video: which to use
- Where to keep it and how often to update it
- Putting the total to work on your policy
- Our perspective: the inventory is a conversation starter
- Have your inventory reviewed for free
- Common mistakes to avoid
- FAQ
- Sources
What people mean by home inventory insurance
When readers search this phrase, they usually want one of three things: how to make an inventory that an insurer will accept, which tool to use, or whether their policy covers what is on the list. All three are answered here.
The part of your policy that pays for belongings is personal property coverage. On a homeowners policy it is called Coverage C, and we explain it in plain language on our personal property coverage page. Renters and condo policies have their own version. The inventory is the evidence that connects the policy to your actual stuff.
It also answers a question many people never ask until after a loss: is the limit high enough? The California Department of Insurance notes that a complete household inventory can show what your contents are worth and whether your coverage is adequate.
Why an inventory changes how a claim goes
After a fire, theft or major water loss, you will be asked what was lost. Memory is a poor witness. Most people can name the television and the sofa, then forget the contents of the closets, the kitchen drawers, the garage shelves and the tools.
The Iowa Insurance Division says an inventory lets claimants submit accurate and detailed reports and receive the actual or replacement cost payment they are entitled to under their policy. The same page warns that without one, insurers may fall back on estimating values, and that can mean being paid less than you should be.
There are three practical benefits:
- Faster, cleaner claims. You hand over a document instead of reconstructing your home from memory while stressed.
- A better coverage decision. Adding up replacement cost shows whether your limit is realistic.
- Spotting items that need extra protection. Jewelry, collectibles, art and similar valuables often have sublimits in a standard policy. Your inventory shows which ones are affected. See our guide on scheduled personal property for how that works.
What to record for every item
The more specific the entry, the easier it is to prove. State agencies agree on the core fields. The Connecticut Insurance Department recommends a brief description, age, purchase price and estimated current value, plus model and serial numbers. It also advises attaching copies of original sales receipts or appraisals.
| Field | What to write | Why it matters |
|---|---|---|
| Room or category | Kitchen, garage, hobby gear | Keeps the list searchable and matches how you would walk through the house |
| Description | Brand, size, color, condition | Lets an adjuster identify the item and its quality level |
| Age and purchase date | Year bought, or "gift, about 2021" | Matters most under actual cash value settlements |
| Purchase price | What you paid | Starting point for replacement estimates |
| Estimated current value | What it would cost to replace today | Drives your coverage limit |
| Model and serial number | From the label or back panel | Proves the specific item existed |
| Proof | Photo, receipt, appraisal | Supports every other field |
Do not skip the unglamorous items. Clothing, shoes, kitchenware, linens, tools and books add up quickly, and replacing all of them at once is where people discover how much they own.
How to build the inventory in an afternoon
You do not need to finish in one sitting, but a fast first pass beats a perfect plan you never start.
Step 1: Pick a method
Choose the format you will actually maintain: an app, a spreadsheet or a video walkthrough. The next section compares them.
Step 2: Go room by room
California recommends walking through each room and recording notes and photos or videos. Illinois suggests grouping possessions into logical categories, such as by hobby or by room. Open every closet, cabinet and drawer on camera. Do the garage, attic, basement and any shed.
Step 3: Capture details as you go
Photograph labels with serial and model numbers while the item is in front of you. Say the description aloud if you are filming: brand, approximate age, what you paid.
Step 4: Add values
Use receipts where you have them. For the rest, look up what a comparable new item costs today. Be honest rather than generous. A padded list can create problems later.
Step 5: Attach the paperwork
Scan receipts, appraisals and warranty cards. Appraisals matter most for jewelry, art, instruments and anything one of a kind.
Step 6: Save and back up
A list that burns with the house is worthless. Storage is covered below.
Apps, spreadsheets and video: which to use
There is no single right answer. Match the tool to your patience.
An app. The National Association of Insurance Commissioners offers a free Home Inventory App that lets you take pictures, group items by room or category, scan barcodes and export your inventory. Many insurers also offer their own apps. Apps work best for people who like structure and want everything in one place.
A spreadsheet. Best if you already live in one. Use the columns in the table above, one tab per room, and a folder of photos named to match. It is simple, portable and easy to print.
Video. The fastest way to cover a whole house. Narrate as you film, open drawers, and pause on valuable items. The weakness is that a video is hard to search, so pair it with a short written list of your most valuable items and their serial numbers.
Many people combine methods: a video of the whole home plus a spreadsheet for electronics, tools and high-value pieces.

Where to keep it and how often to update it
The California guide recommends keeping an updated copy in at least two places, such as a fire-resistant box at home, a locked cabinet at work, or with a relative or friend. It also suggests updating the inventory three to four times a year and adding major purchases as soon as possible.
A simple routine:
- Store the master file in cloud storage you can log into from any device.
- Keep a second copy on a drive or in a safe-deposit box away from your home.
- Tell one trusted person where it is.
- Set a quarterly reminder, and add big purchases the week you buy them.
If you stage a move or keep belongings elsewhere, your inventory should include them too. Items in a rented unit are a separate question: read up on self-storage insurance basics and then ask your agent whether your policy extends to property away from home.
Putting the total to work on your policy
The inventory is only useful if you act on the number at the bottom. Compare it with your current personal property limit. If the total is higher, you are underinsured on contents. If you recently bought furniture, started a hobby or received valuable gifts, the gap may be larger than you think.
Then check how your policy pays. The Illinois Department of Insurance explains that replacement cost coverage pays what it costs to replace an item minus the deductible, while actual cash value pays the depreciated value at the time of loss. On a ten-year-old sofa, those two settlements can be far apart. Your inventory shows which one matters for your home.
A few other places inventories change decisions:
- Renters. Many renters underestimate their belongings. Our renters insurance page explains what the coverage does.
- Condo owners. Contents coverage is separate from the building, and assessments are a different risk. See how to size loss assessment coverage.
- Before renovations. New kitchens and finishes change what your home contains. Read what to do before work starts.
- Working from home. Business equipment at home is often limited under a standard policy. Our post on home-based business coverage covers that.
Our perspective: the inventory is a conversation starter
We are an independent agency, and we place coverage with more than 25 A-rated carriers. In practice, the inventory is rarely the problem. The problem is that people finish it, put it in a folder, and never compare it with what their policy actually promises.
We like to treat the inventory as the first page of a coverage review. Once we see what you own, we can explain in plain language how your policy treats it: what the limit is, whether it pays replacement cost or depreciated value, which items have sublimits and what is excluded. Sometimes the answer is that you are fine. Sometimes it is a gap you would rather find now than during a claim.
We also stay with clients when they file. A tidy inventory makes our job during a claim easier, because we can point to documentation instead of arguing about what a ruined room contained. For how that process runs, see our step-by-step claims guide.
— David
Have your inventory reviewed for free
If you have finished a list, or even just a rough total, we will compare it with your current policy at no charge and no obligation. We look for coverage gaps, explain the terms without jargon and, if a better fit exists across the carriers we work with, show you your options. Start with a free policy review, or request insurance quotes if you are ready to compare. If you own, our homeowners insurance page is the place to begin.
We are licensed in 17 states, including Illinois, Florida and Washington.
Common mistakes to avoid
- Waiting for a reason. Inventories are hardest to build after a loss, when there is nothing left to photograph.
- Storing it only at home. The record needs to survive the same event your belongings do.
- Listing categories instead of items. "Kitchen stuff, $1,000" is hard to defend. Break it down.
- Forgetting to update. A list from five years ago omits your newest and likely most valuable purchases.
- Ignoring valuables. Jewelry, collectibles and art deserve appraisals and a conversation about scheduling.
- Never reading the policy. An accurate inventory paired with the wrong settlement type still leaves you short.
FAQ
How do I do a home inventory for insurance?
Walk through each room and photograph or film every item, including what is inside closets and drawers. Write a short description, age, purchase price, estimated current value, and model and serial number for each one. Attach receipts or appraisals, then store a copy away from your home.
What kind of insurance covers my belongings?
Homeowners policies cover personal property under Coverage C, and renters and condo policies have equivalent contents coverage. Your policy sets a limit and decides whether you are paid replacement cost or depreciated value. Valuables like jewelry may need extra coverage, so ask your agent.
Do I need a home inventory if I rent?
Yes. Renters insurance covers your belongings, and an inventory helps you pick a sensible limit and document a loss. Illinois' insurance department also recommends organizing possessions by room or category for renters.
How often should I update my home inventory?
California's insurance department suggests updating three to four times a year and adding major purchases as soon as you can. Also revisit it after a renovation, a big gift or a move.
Is the NAIC home inventory app enough?
It can be, if you use it consistently. It lets you capture photos, organize items by room, scan barcodes and export your list. Keep an exported copy somewhere other than your phone.
Sources
- California Department of Insurance: Home Inventory guide
- Iowa Insurance Division: The importance of a home inventory
- Connecticut Insurance Department: Consumer Alert, May 14, 2024
- Illinois Department of Insurance: Renter's insurance
- NAIC: Home Inventory App
- Self-storage insurance: what you need and what to skip