
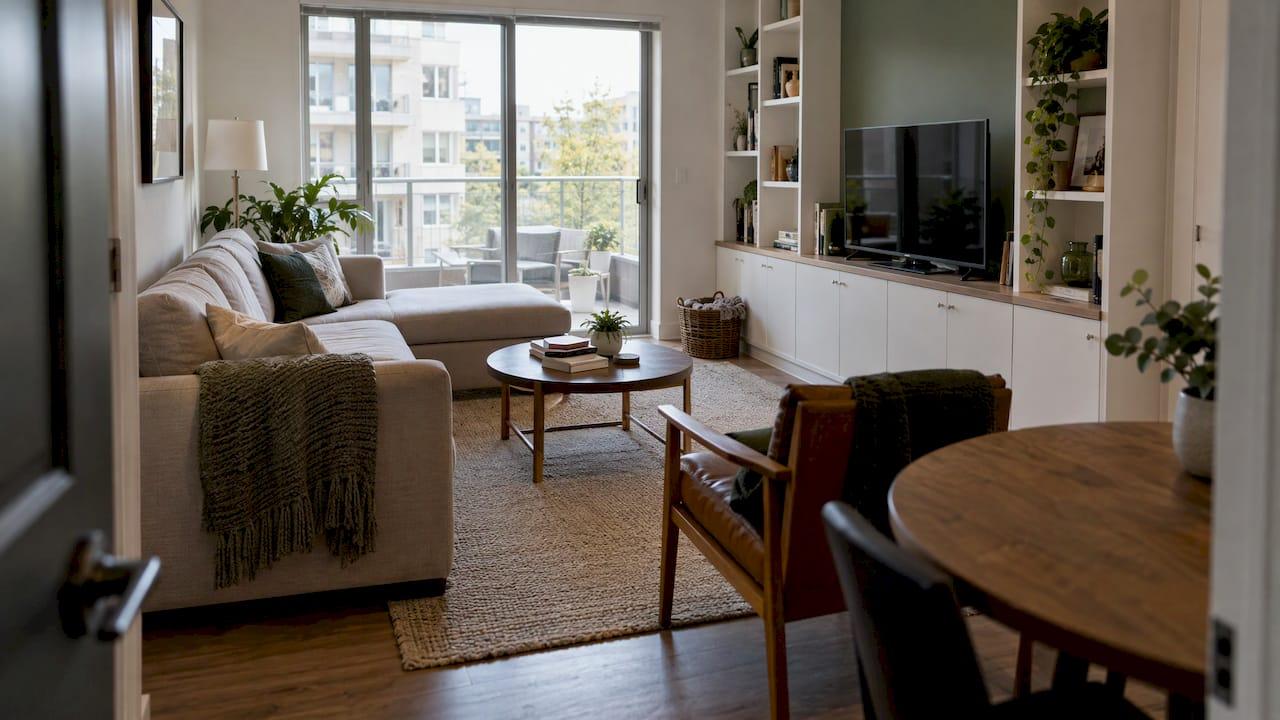
Dwelling coverage pays to repair or rebuild the structure you are responsible for. Personal property coverage pays to replace the things you own inside it, such as furniture, clothing and electronics. They are two separate lines on your policy, each with its own limit. A claim after a fire often draws on both at once, so a gap in either one can leave you paying out of pocket.
This guide explains the split with a focus on condo owners (HO-6 policies), where the line between the two is easiest to get wrong. It also covers the other coverages that sit beside them and how to choose a limit for each.
TL;DR
- Dwelling (Coverage A) insures the structure and fixed parts of your home. In a condo, that means the parts of the unit you are responsible for under your association's rules.
- Personal property (Coverage C) insures what you own and could carry out the door: furniture, clothes, electronics, sports gear.
- Set the dwelling limit by rebuilding cost, not purchase price. Set the personal property limit by what it would cost to replace your belongings.
- Condo owners should read the association's master policy and governing documents first, because they decide where your dwelling coverage starts.
- Jewelry, cash, collectibles and similar items often carry small sublimits, so review them separately.
Table of Contents
- The difference in one table
- What dwelling coverage insures
- What personal property coverage insures
- Where the line falls in a condo
- A worked example: a kitchen fire in a condo
- What else your policy covers beyond the two
- How to choose your dwelling limit
- How to choose your personal property limit
- Do you need both coverages?
- Our perspective
- Get your limits checked
- FAQ
- Sources
The difference in one table
| Dwelling coverage (Coverage A) | Personal property coverage (Coverage C) | |
|---|---|---|
| What it insures | The structure and permanently installed parts | Belongings you own or use |
| Typical examples | Walls, floors, cabinets, built-in fixtures | Sofa, TV, laptop, clothing, bikes |
| How you set the limit | Cost of labor and materials to rebuild | Replacement value of everything you own |
| Moves with you? | No, it is tied to the property | Often has limited coverage away from home |
| Common trouble spot | Unclear who insures what in a condo | Underestimating total value, special sublimits |
What dwelling coverage insures
Dwelling coverage, also called Coverage A, is the part of the policy that pays to repair or rebuild the physical home after a covered loss. In a house, that means the roof, walls, foundation and attached structures. A guide from a consumer-focused insurance site describes it the same way and stresses that the limit should reflect rebuild cost rather than market value.
In a condo, the picture shrinks and shifts. You do not own the roof or the foundation in the same way, and the association insures much of that. Your dwelling coverage protects the part of the unit you are responsible for, such as interior walls, floors and cabinets, according to American Family's condo coverage page. A regulatory example makes the wording concrete: New Jersey's standard condominium policy language says Coverage A applies to property permanently installed in the unit that the association's policy does not cover.

Policy forms spell this out in more detail. One HO-6 form filed with the Nevada Department of Insurance lists built-in components, attached fixtures, alterations, additions, improvements and permanently attached floor coverings that are the owner's financial responsibility under the condo declaration. Forms differ by carrier and state, so the exact list in your policy is what counts.
Examples of what typically falls under dwelling
- Drywall and interior paint
- Hardwood, tile or other attached flooring
- Built-in cabinets and countertops
- Light fixtures and plumbing fixtures
- Upgrades you made after buying, such as a remodeled kitchen
If you can't unscrew it, unplug it or carry it out, it usually belongs to dwelling rather than personal property.
What personal property coverage insures
Personal property coverage, called Coverage C, helps replace belongings that are damaged, stolen or destroyed in a covered loss. The New Jersey language names furniture, clothing, computers and TVs as examples. Our glossary entry on Coverage C gives the plain-English version.

This coverage follows you. The Nevada form covers property owned or used by an insured anywhere in the world, but limits property away from the residence, including items usually kept at another insured residence or taken outside the United States, to 10 percent of Coverage C with a $3,000 minimum, subject to stated exceptions. Other carriers set these terms differently.
Sublimits: where valuables get caught
Standard personal property coverage often caps certain categories. The same Nevada form shows examples of special limits: $300 for money and precious metals, and $1,500 each for watercraft and certain trailers. The exact numbers vary by form and state, but the pattern is common. Cash, collectibles, jewelry, furs and silverware often have limited coverage and may need an endorsement or separate policy, as Travelers' condo FAQ notes.
If you own a ring, a watch collection, art or musical instruments, read how scheduling personal property works. For larger collections, our high-value and specialty coverage is built for that situation.
Where the line falls in a condo
The most common confusion is not between Coverage A and Coverage C. It is between your policy and the association's. The Washington Office of the Insurance Commissioner explains that condo owners typically have two policies: the owner's HO-6 policy and the association's master policy, each covering different parts of the unit and community.
The master policy decides how much of the unit you must insure. Associations generally fall into a few patterns, and which one applies is written in your declaration and bylaws:
- Bare-walls style: the association insures the outer structure, and you insure everything from the studs inward. Your dwelling limit has to be larger.
- Original-condition style: the association insures the interior as it was originally built, and you insure upgrades and anything beyond that standard.
- All-in style: the association insures most of the interior, and your dwelling limit can be smaller, though it still matters for improvements and for gaps.
These labels vary between associations and carriers, so treat them as a way to read your documents, not as a substitute. A walk through how unit-owner and association policies work together can help you spot the gaps before a claim. Ask your property manager for the master policy declarations page and the governing documents, then bring them to your review.
We cover this in detail on our Illinois condo insurance page.
A worked example: a kitchen fire in a condo
Imagine a stovetop fire in a condo with a bare-walls master policy. Here is how the claim could split. The amounts are illustrative, not from any real policy.
| Damaged item | Which coverage responds | Why |
|---|---|---|
| Cabinets, countertops, drywall | Dwelling (Coverage A) | Fixed parts of the unit you insure |
| Refrigerator and built-in oven | Often dwelling, depending on your form | Built-in appliances are commonly treated as part of the unit |
| Dining table, chairs, small appliances | Personal property (Coverage C) | Movable belongings |
| Hotel and meals while repairs are done | Loss of use | Living expenses after an unlivable loss |
The same event can trigger several parts of the policy. That is why a dwelling limit that looks adequate on its own can still leave you short if contents are underinsured, and the reverse.
What else your policy covers beyond the two
Dwelling and personal property are the headline coverages, not the whole policy. The California Department of Insurance guide lists common condo-owner coverages including loss of use, personal liability, medical payments to others and loss assessment. The Washington OIC describes additional living expense coverage as paying for temporary relocation after a covered loss makes the unit unlivable.
Loss assessment deserves special attention. The Washington OIC notes the owner can face a charge from the association even when the damage is to common property rather than to your belongings. If the master policy's limit is exceeded or a deductible must be shared, the association can bill owners. Our guide to sizing loss assessment coverage offers a formula for choosing a limit.
Flood, earthquake, normal wear and tear and similar causes of loss are commonly excluded from standard policies. Your policy lists its exclusions, and some risks can be added separately. For example, here is what we explain about water backup coverage.
How to choose your dwelling limit
The California Department of Insurance says the amount for rebuilding should be based on the cost of labor and materials, not the purchase price or real-estate market value. A condo that sold for a high price because of its view or neighborhood does not cost more to put drywall and cabinets back into.
A practical process:
- Get the governing documents. Find out exactly what the association insures and what you must insure.
- List everything inside the walls you are responsible for. Flooring, cabinetry, countertops, fixtures, built-in appliances, and upgrades by you or prior owners.
- Price the rebuild. Use a contractor's per-square-foot estimate for your area and finish level, not the listing price.
- Choose the limit with room for rising costs. Ask about options that adjust for construction inflation.
One content site suggests most condo owners need at least $100,000 in dwelling coverage, but it also says the right amount depends on what the master policy already covers. Treat any such number as a starting point for the conversation, not a recommendation for your unit.
How to choose your personal property limit
Personal property limits should reflect what it costs to replace your belongings, and an inventory is the way to get there, as Travelers advises. Walk through each room and note what you own, roughly what it cost new and what it would cost to replace today. People consistently underestimate the total. Add up clothing, kitchenware, electronics, bedding, tools and decor, and the sum usually surprises them.
Build the list with photos or video. We explain how in our home inventory guide, and the same list speeds up a claim if you ever need one.
Replacement cost vs actual cash value
This choice changes how much a claim pays. The Texas Real Estate Research Center explains that replacement cost is generally the cost to repair or replace with like kind and quality without depreciation. Actual cash value is replacement cost minus depreciation, and policy wording controls. A five-year-old couch under actual cash value pays what a five-year-old couch is worth, not what a new one costs. Many people prefer replacement cost on belongings for that reason, if their carrier offers it at a price they like.
Do you need both coverages?
If you own a condo or house, yes. A lender typically requires coverage on the structure, and the belongings inside are yours to protect. Renters have no structure to insure, so they carry personal property and liability only. If that's you, see our renters insurance page. Homeowners can see how Coverage A and C fit within a full policy on our homeowners insurance page. To understand how the form of your policy changes which causes of loss are covered, read about named perils vs open perils.
Our perspective
We see the same mistake in policy reviews again and again. People treat the dwelling limit and the contents limit as one number, or they assume the association's policy covers what theirs does not.
Because we are an independent agency that compares options across more than 25 A-rated carriers, we can show you how different forms word dwelling and personal property, and where each one draws its lines. That matters most for condos, where the paperwork is the product.
Our approach is to read your declarations page and your association's documents in plain language, point out gaps, and only then talk about quotes. The review costs you nothing, and we stay with you through the claim.
David
Get your limits checked
If you're unsure whether your dwelling and personal property limits match your home, we will compare your current coverage against your documents at no charge. We are licensed in Illinois, Florida and Washington among our 17 states, and we explain every option without jargon.
Start with a free policy review, or request insurance quotes if you're ready to compare carriers.
FAQ
Is a refrigerator dwelling or personal property?
It depends on the form and how the appliance is installed. Built-in appliances are often treated as part of the dwelling, while freestanding ones are often treated as personal property. Check your policy wording or ask us to read it with you.
Does dwelling coverage cover my furniture?
No. Furniture, clothing and electronics fall under personal property coverage. Dwelling coverage is for the structure and permanently installed parts of the home or unit.
Is my condo's dwelling limit based on what I paid for it?
No. The California Department of Insurance says the amount should be based on the labor and materials needed to rebuild, not the purchase price or market value. Your association's documents determine which parts you must rebuild.
What does condo insurance cover besides dwelling and personal property?
Common additional coverages include loss of use, personal liability, medical payments to others and loss assessment. Your policy lists the exact coverages and limits.
Sources
- MoneyGeek: What Is Dwelling Coverage?
- American Family: Condo insurance coverage
- N.J. Admin. Code Tit. 11, ch. 2, subch. 41, Appendix, exh. B
- Condominium Unit-Owners Form, Nevada Department of Insurance
- Travelers: Condo insurance FAQs
- Washington Office of the Insurance Commissioner: How condo insurance works
- California Department of Insurance: Residential Insurance guide
- Texas Real Estate Research Center: String of Perils
- LegalClarity: How much condo insurance do I need